
The Kelly Criterion provides the mathematically optimal capital allocation fraction that maximizes the asymptotic long-term geometric compounding rate of a trading bankroll while guaranteeing zero probability of gambler's ruin. In binary prediction derivatives, where outcomes settle strictly to 0 or 1, Kelly sizing protects quantitative traders against the devastating tail risks of overbetting and capital-inefficient longshot fading.
1. Logarithmic Utility and Geometric Compounding
First formulated by John L. Kelly Jr. at Bell Laboratories in 1956, the criterion translates Claude Shannon's information theory directly into capital allocation. Consider a repetitive investment process over discrete trading periods t ∈ {1, 2, ..., T}. Let W_t denote portfolio bankroll at period t. If an investor allocates a constant fraction f of total capital to positive expected value opportunities, the wealth trajectory follows a geometric compounding process:
W_T = W_0 * ∏_{t=1}^T (1 + f * R_t)
Where R_t represents the stochastic rate of return on the trade. Maximizing arithmetic return leads to extreme leverage and inevitable asymptotic bankruptcy due to volatility drag. Instead, Kelly maximizes the expected value of the logarithmic utility of terminal wealth:
G(f) = E[ln(W_{t+1} / W_t)] = p * ln(1 + f * b) + (1 - p) * ln(1 - f)
Where p is the true probability of event occurrence, q = 1 - p is the failure probability, and b is the net payout odds per dollar risked.
2. Derivation of the Binary Contract Kelly Formula
In a standardized binary prediction market, contract shares are purchased at clearing price P_m ∈ (0, 1) and settle to exactly $1.00 upon success or $0.00 upon failure.
When buying shares at price P_m, risking $1.00 yields 1 / P_m total shares. If the contract resolves favorably, the gross payoff is 1 / P_m dollars. The net profit per dollar risked (the decimal payout odds b) is:
b = (1.00 - P_m) / P_m
Substituting this specific payout structure into the general Kelly objective function G(f):
G(f) = p * ln[1 + f * ( (1 - P_m) / P_m )] + (1 - p) * ln[1 - f]
To find the optimal capital fraction f^* that maximizes growth rate G(f), we compute the first derivative with respect to f and set it equal to zero:
dG / df = [ p * b / (1 + f * b) ] - [ (1 - p) / (1 - f) ] = 0
Solving this linear algebraic equality directly for f^* yields:
f^* = (b * p - q) / b
Replacing b = (1 - P_m) / P_m and q = 1 - p into the expression:
f^* = [ ( (1 - P_m) / P_m ) * p - (1 - p) ] / [ (1 - P_m) / P_m ]
f^* = [ p - P_m * p - P_m + P_m * p ] / (1 - P_m)
f^* = (p - P_m) / (1 - P_m)
This elegant formulation reveals that in any binary derivative market, the mathematically optimal Kelly fraction is simply the objective probability edge (p - P_m) divided by the loss probability implied by the market price (1 - P_m).
3. Comprehensive Binary Kelly Sizing Matrix
The table below shows full Kelly, half Kelly (0.5x) and quarter Kelly (0.25x) fractions for a range of market prices and assumed true probabilities, with the expected growth per trade at each fraction:
| Market Price (P_m) | True Prob (p) | Absolute Edge | Full Kelly (f*) | Half Kelly (0.5x) | Quarter Kelly (0.25x) | Growth per Trade (Full / Half / Quarter) |
|---|---|---|---|---|---|---|
| $0.10 | 0.18 (18%) | +8.0% | 8.89% | 4.44% | 2.22% | +2.95% / +2.33% / +1.44% |
| $0.25 | 0.35 (35%) | +10.0% | 13.33% | 6.67% | 3.33% | +2.47% / +1.90% / +1.13% |
| $0.40 | 0.50 (50%) | +10.0% | 16.67% | 8.33% | 4.17% | +2.04% / +1.54% / +0.90% |
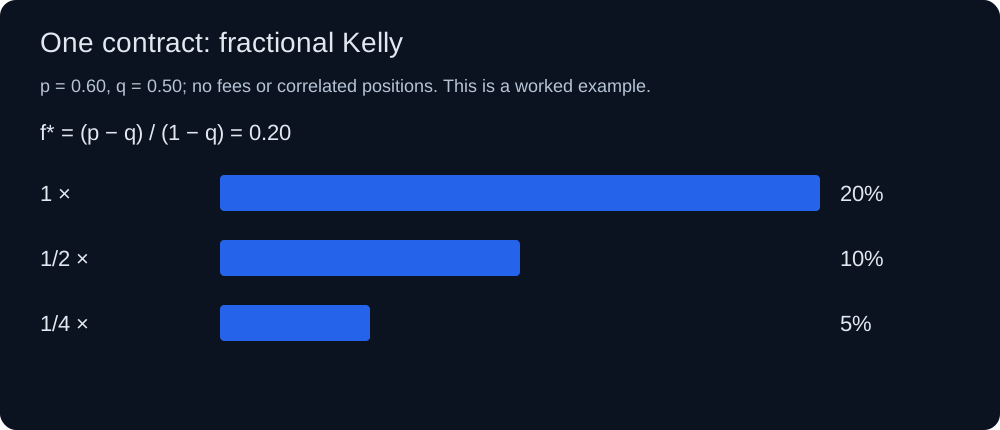
| $0.50 | 0.60 (60%) | +10.0% | 20.00% | 10.00% | 5.00% | +2.01% / +1.50% / +0.88% |
| $0.65 | 0.75 (75%) | +10.0% | 28.57% | 14.29% | 7.14% | +2.32% / +1.70% / +0.98% |
| $0.80 | 0.88 (88%) | +8.0% | 40.00% | 20.00% | 10.00% | +2.26% / +1.62% / +0.91% |
| $0.90 | 0.95 (95%) | +5.0% | 50.00% | 25.00% | 12.50% | +1.67% / +1.16% / +0.64% |
Growth is the expected log growth of the bankroll per trade, G(f) = E[ln(W_{t+1} / W_t)], computed with the formula in section 1 and assuming p is exactly right. In these rows half Kelly keeps between 69.7% and 79.0% of full-Kelly growth and quarter Kelly between 38.5% and 48.8%; the familiar 75% and 43.75% are the limits for small edges. The figures also assume such trades can be repeated independently. They are computed by a short script that you can rerun; an earlier version of this table showed growth rates that did not match the formula.
4. The Capital Inefficiency of Shorting Longshots: The Polymarket Fade Trap
A common instinct among new prediction market traders is to "fade" low-probability longshots by buying No shares on contracts whose Yes side trades at 3¢ to 5¢ ($0.03 to $0.05). It feels like "guaranteed 95% probability money."
The payoff structure says otherwise. Fading longshots is a capital inefficiency trap: small capped gains, capital locked until resolution, and rare losses of the whole stake:
A. Capital Velocity and Asymmetric Locking
To short a $0.05 event, a trader buys No shares at $0.95. Deploying $10,000 locks up capital for weeks or months until resolution, for a maximum gross profit of $526.32 (a 5.26% return). Meanwhile the whole $10,000 is frozen and cannot be used elsewhere.
B. The Asymmetry of Black Swan Tail Events
If the longshot happens (a political upset, a sudden court ruling, an unexpected merger), the position loses 100% of the invested principal ($10,000). A single loss wipes out the profit of 19 winning trades ($10,000 / $526.32 = 19.0).
C. Kelly Analysis of Fading Longshots
Applying the Kelly formula to a No contract at $0.95 where the trader estimates the true probability of No at 96.0% (Yes at 4.0%, while it trades at 5.0%):
f^* = (p - P_m) / (1 - P_m) = (0.96 - 0.95) / (1 - 0.95) = 0.01 / 0.05 = 0.20 (20.0%)
Full Kelly says to put 20% of the bankroll into a position that earns at most 5.26%, on an edge of one percentage point. The size rests entirely on that thin edge: if the estimate is off by 1.5 points (true p = 94.5% instead of 96.0%), the edge turns negative and the position loses money on average.
D. What Real Prices Say
Whether fading is a losing trade or a small edge depends on whether longshots are overpriced. We checked on 3,236 resolved Polymarket markets (volume of at least $50,000, March 2023 to October 2026). Buying No a day before close on contracts whose Yes price was 3–5¢ returned −0.96% on average before fees (95% interval −5.20% to +3.28%); 5 of the 105 contracts resolved Yes. Across all contracts under 10¢ the average was +0.51% (+0.26% to +0.77%), mostly from contracts under 1¢ whose maximum gain is a fraction of a cent, and outside multi-outcome events it was +0.06% (−0.64% to +0.76%). In other words, the fade earned close to nothing per dollar committed and lost the whole stake in the rare upset. The data and method are in our calibration study.
5. The Fractional Kelly Imperative (Half vs. Quarter Sizing)
Full Kelly (f^*) maximizes expected geometric growth only if the probability p is known exactly. Real traders estimate p with error. If p is overestimated, the stake exceeds the true optimum, and beyond roughly twice the true Kelly fraction expected growth turns negative:
f > 2 * f^* (approximately) ==> G(f) < 0: the bankroll shrinks in the long run
Full Kelly is also very volatile. In the standard continuous-time approximation, a trader betting 1.0x Kelly has a 33.3% chance of losing half the bankroll before doubling it, and a 50% chance of being down by half at some point.
To cut drawdowns while keeping most of the growth, many professional traders use Fractional Kelly (same approximation):
- Half Kelly (0.50 * f^*): Keeps 75% of the maximum growth rate with a quarter of the variance (half the volatility). The chance of halving before doubling falls from 33.3% to 11.1%.
- Quarter Kelly (0.25 * f^*): Keeps 43.75% of the maximum growth with 6.25% of the variance (a quarter of the volatility). The chance of halving before doubling falls to 0.78%.
6. Multi-Contract Portfolio Kelly with Correlation Matrix
When an investor holds simultaneous positions across multiple binary prediction markets (e.g., electoral outcomes across several swing states or interest rate decisions across successive quarters), event outcomes are rarely independent.
Let f = [f_1, f_2, ..., f_n]^T denote the vector of capital fractions, and let Σ represent the covariance matrix of contract returns. The multi-asset Kelly objective function expands into:
max_f [ f^T * μ - (1/2) * f^T * Σ * f ] subject to ∑ f_i ≤ 1.0
Where μ is the vector of expected returns μ_i = (p_i - P_{m,i}) / P_{m,i}. In positive correlation regimes (ρ_{ij} > 0), simultaneous Kelly allocations must be scaled down substantially to prevent systemic portfolio drawdown when correlated macro events resolve against the book.
7. Interactive Kelly Sizing Calculator and Bankroll Management
To eliminate emotional guesswork and apply mathematical rigor to every trade execution, quantitative investors automate their position sizing using parameterized Kelly algorithms.
You can model your exact edge, compute full, half, and quarter Kelly fractions, and evaluate capital ruin probabilities using our zero-runtime client-side tool:
Launch Binary Kelly Criterion Calculator →
By adhering strictly to fractional Kelly principles and avoiding the low-yield fade trap, quantitative traders maximize long-term wealth compounding while preserving capital through every market cycle.
