
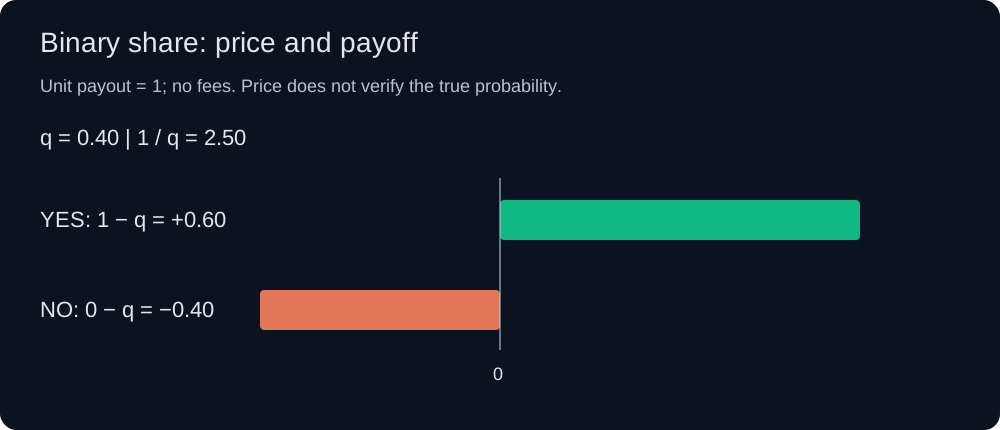
Prediction markets represent dynamic, continuous-time mechanisms engineered to aggregate dispersed private information into calibrated consensus probability distributions. In any cash-settled binary contract, the price serves as the market's estimate of the probability of the event. Under risk neutrality and with no fees it equals that probability; real prices drift from it at the extremes, as the data in section 7 show.
1. The Binary Derivative Contract Architecture
At its foundational core, a binary outcome contract is an elementary Arrow-Debreu security. Let Ω denote the complete sample space of a future real-world event, partitioned into mutually exclusive and exhaustive resolution states:
Ω = { S_Yes, S_No }, where P(S_Yes) + P(S_No) = 1.000
The terminal payout function Φ(S) of the contract is state-contingent:
Φ(S_Yes) = $1.00
Φ(S_No)  = $0.00
Under the assumption of risk neutrality, the market clearing price P_t ∈ (0, 1) at timestamp t satisfies the discounted conditional mathematical expectation:
P_t = e^{-r(T-t)} * E^Q[Φ(S) | F_t]
Where r represents the annualized risk-free interest rate, T is the expiration timestamp, Q is the risk-neutral martingale probability measure, and F_t represents the filtration of all publicly accessible market information up to time t. Over horizons where r(T-t) approaches zero, the price simplifies directly into the market-implied probability:
P_t = Q(S = S_Yes | F_t)
Under these assumptions, a price of $0.62 means an implied probability of 62%. Real prices deviate from this because of fees, the bid-ask spread and risk preferences (see section 7). If the market is weakly efficient, no trading strategy can systematically extract positive risk-adjusted excess returns without possessing private asymmetric information or statistical modeling superior to the collective marginal trader.
2. Automated Market Maker Mechanics: CPMM vs. LMSR
Modern prediction markets deploy two distinct algorithmic market maker architectures to supply continuous liquidity without relying solely on limit order book depth:
A. The Constant Product Market Maker (CPMM)
Used by early decentralized prediction venues (Polymarket ran such pools in its early years and now uses a central limit order book), the CPMM maintains liquidity invariant pools of collateral x (representing Yes tokens) and y (representing No tokens) governed by:
x * y = k
When an incoming participant commits Δc units of currency to purchase Yes contracts, the marginal instantaneous price p_{Yes} is determined dynamically by the ratio of outstanding reserves:
p_{Yes} = y / (x + y), p_{No} = x / (x + y)
Because y / (x + y) + x / (x + y) = 1.000, the condition p_{Yes} + p_{No} = 1.000 is preserved deterministically at every point along the bonding curve, eliminating synthetic arbitrage within the native pool itself.
B. Hanson's Logarithmic Market Scoring Rule (LMSR)
Pioneered by Robin Hanson, LMSR provides bounded maximum loss for market organizers while guaranteeing infinite liquidity across multiple combinatorial outcomes. For a contract state vector q = (q_1, q_2, ..., q_n) with liquidity parameter b > 0, the aggregate cost function C(q) is defined as:
C(q) = b * ln(∑_{i=1}^n e^{q_i / b})
The marginal instantaneous price p_i of purchasing an infinitesimal fraction of outcome i is the partial derivative of cost with respect to quantity:
p_i = ∂C / ∂q_i = e^{q_i / b} / (∑_{j=1}^n e^{q_j / b})
This formulation is mathematically equivalent to the Softmax function in machine learning. It guarantees that all marginal prices remain strictly positive (p_i > 0) and sum precisely to unity (∑ p_i = 1.000), preventing probability distortions regardless of transaction size.
3. Deconstructing Operator Overround and the Vig
Unlike peer-to-peer prediction exchanges where participants trade directly against each other, traditional commercial bookmakers embed a structural house advantage known as the overround or vigorish (vig). The overround O is expressed as:
O = ∑_{i=1}^n (1 / d_i) - 1.000
Where d_i represents the decimal payout odds for outcome i. For example, if a binary sportsbook market quotes Yes at 1.85 and No at 1.85:
P_{raw}(Yes) = 1 / 1.85 = 0.5405 (54.05%)
P_{raw}(No)  = 1 / 1.85 = 0.5405 (54.05%)
Sum = 0.5405 + 0.5405 = 1.0810 (8.10% overround)
To recover true fair probabilities from commercial bookmaker odds, quantitative researchers apply three rigorous normalization methodologies:
- Proportional Normalization: Assumes the operator spreads the margin in proportion to each price: P_{fair, i} = P_{raw, i} / ∑ P_{raw, j}. Here, P_{fair} = 0.5405 / 1.0810 = 0.5000 (50.00%).
- Odds-Ratio Method: Assumes the margin multiplies every outcome's odds ratio p / (1 - p) by the same factor, so, compared with proportional normalization, removing the margin lowers longshot prices relatively more.
- Shin's Model: Assumes a share z of the money comes from insiders who know the outcome. To cover expected losses to them, the bookmaker loads relatively more margin onto longshots, so removing the margin lowers longshot prices more than favourite prices.
Real bookmaker margins are of the same order as this example. In our snapshot of 76 Yes/No questions on 1win Markets (21 October 2026, one location), the median overround was 7.5%. On exchanges such as Polymarket and Kalshi the cost comes instead from the taker fee and the bid-ask spread. Details and sources are in our fee comparison.
4. Mathematical Odds Equivalence and Conversion Table
The table below details exact mathematical conversions between contract cents, implied probability, fair decimal multipliers, and American moneyline conventions:
| Contract Price ($) | Implied Probability | Fair Decimal Multiplier | American Moneyline | Break-Even Required Win % |
|---|---|---|---|---|
| $0.05 | 5.0% | 20.00x | +1900 | 5.00% |
| $0.10 | 10.0% | 10.00x | +900 | 10.00% |
| $0.20 | 20.0% | 5.00x | +400 | 20.00% |
| $0.35 | 35.0% | 2.86x | +186 | 35.00% |
| $0.50 | 50.0% | 2.00x | +100 | 50.00% |
| $0.65 | 65.0% | 1.54x | -186 | 65.00% |
| $0.80 | 80.0% | 1.25x | -400 | 80.00% |
| $0.95 | 95.0% | 1.05x | -1900 | 95.00% |
5. Mathematical Derivation of Expected Value (EV) and Portfolio Variance
When an investor's proprietary probability model indicates that true event probability p_{true} diverges from the market clearing price P_m, a measurable mathematical edge emerges.
Let S represent total capital committed to buying shares at price P_m. The quantity of shares acquired is N = S / P_m. The contract yields a discrete payoff upon binary resolution:
Payoff_{Win}  = N * $1.00 = S / P_m
Payoff_{Loss} = $0.00
The discrete mathematical Expected Value (EV) is given by:
EV = p_{true} * (Payoff_{Win} - S) - (1 - p_{true}) * S
EV = p_{true} * [ S * (1 - P_m) / P_m ] - (1 - p_{true}) * S
EV = S * [ (p_{true} - P_m) / P_m ]
The theoretical return on investment (Edge / ROI) is expressed independently of bet size:
ROI_{EV} = (p_{true} - P_m) / P_m
However, positive EV is accompanied by statistical variance. The single-period portfolio return variance σ^2 of a binary contract position is:
σ^2 = p_{true} * (1 - p_{true}) * [ 1 / (P_m)^2 ]
Notice that as P_m decreases toward zero (extreme longshots), the return variance explodes quadratically. This mathematical truth demonstrates why longshot betting exhibits extreme tail volatility, necessitating strict fractional position sizing through the Kelly Criterion.
6. Liquidity Depth, Price Impact, and Slip Curves
In real-world decentralized markets, execution price is not stationary. Every trade of finite size Δx impacts the pool state along the CPMM invariant curve. For an order of size Δc purchasing Yes tokens, the average execution price P_{avg} is strictly higher than the spot price P_{spot}:
P_{avg} = Δc / Δy = P_{spot} * [ 1 + (1 - P_{spot}) * (Δc / y) + O((Δc / y)^2) ]
Where y is the pool's reserve of No tokens in the Yes/No pool of section 2A. In a balanced pool holding L tokens of each outcome (P_{spot} = 0.5), this reduces to P_{spot} * [1 + Δc / (2 * L)]: spending 1% of L raises the average price by about 0.5%. If an algorithm executes an order that is large relative to the pool, the effective edge ROI_{EV} degrades according to:
ROI_{net} = (p_{true} - P_{avg}) / P_{avg} - Fee_{protocol}
Quantitative desks must compute the critical order size Δc^* where ROI_{net} equals zero. Any order exceeding Δc^* turns a positive-expectation trading opportunity into negative expected value due to self-induced slippage.
7. What Real Prices Show: Calibration and Timing
We tested implied probabilities directly on 3,236 resolved Yes/No markets on Polymarket (volume of at least $50,000, closed between March 2023 and October 2026). Read as probabilities, prices did well overall but not at every level. Contracts under 10¢ a day before close averaged 0.86% and resolved Yes 0.37% of the time, so longshots were overpriced; contracts at 50–80¢ resolved Yes more often than their prices implied. The full tables are in our calibration study.
Prices also sharpen as resolution approaches. Seven days before close, 79% of markets were priced below 10¢ or at 90¢ and above, and the Brier score was 0.0435; 24 hours before close the share was 86% and the Brier score 0.0259. The market keeps absorbing news until the end.
For comparison with polls, the best-known long-run study (Berg, Nelson and Rietz, 2008) compared Iowa Electronic Markets prices with 964 national polls across five US presidential elections and found the market closer to the final result in 74% of the comparisons. Prices are not free of bias, though: the favourite-longshot pattern above, fees and the cost of locking up capital until resolution all pull prices away from probabilities.
8. Interactive Probability Converter & Execution Framework
To operationalize these mathematical equations in production trading environments, researchers utilize automated conversion pipelines that ingest raw order-book feeds, extract fair probabilities, and monitor implied volatility surfaces in real time.
You can model your own implied probability scenarios, calculate fair bookmaker margins, and determine risk-adjusted positive expected value using our zero-latency client-side tool:
Launch Market-to-Probability Converter →
By mastering implied probability mechanics, quantitative market participants strip away operator fees, isolate statistical mispricings, and execute mathematically sound trades across the global event derivative landscape.
